A Quarter Review
The S&P 500 increased 2.7% during the fourth quarter and marked the third straight year of 15% returns for the index.
The top performing sectors were Health Care (11.7%), Communications Services (7.3%), and Financials (2.0%). The worst performing sectors were Real Estate (-2.5%), Utilities (-1.4%), and Consumer Staples (0.0%).
Performance Summary
The Johnson Equity Income Strategy posted a return of 2.4%, net of fees, underperforming the aforementioned 2.7% return of the S&P 500 in the fourth quarter. Sector allocation was a drag on relative performance while stock selection was positive. The Strategy was materially underweight Communication Services during the quarter, which was by far the largest drag on an allocation basis given the sector’s strong performance, albeit primarily due to one security. In contrast, the Strategy’s large underweight to Technology was positive to relative performance during the quarter, reflective of the performance dispersion witnessed among the index’s largest constituents in 2025. The Strategy also benefited from an overweight in Health Care in addition to an underweight in Real Estate, with the former as the best performing sector and the latter as the worst performing sector during the quarter, as mentioned above.
Notwithstanding, the S&P 500 continues to be extraordinarily concentrated. As such, given our more diversified portfolio construction discipline, our relative returns continue to be impacted significantly by structural underweights to the largest names in the index. This includes one of the larger U.S. hyperscalers that was a significant negative contributor to relative performance due to being underweight. In contrast, notable positive contributors for the quarter included two other U.S. hyperscalers with double-digit negative returns that we did not own. However, the largest positive contributor during the quarter was a recently added Consumer Discretionary stock within the restaurant industry.
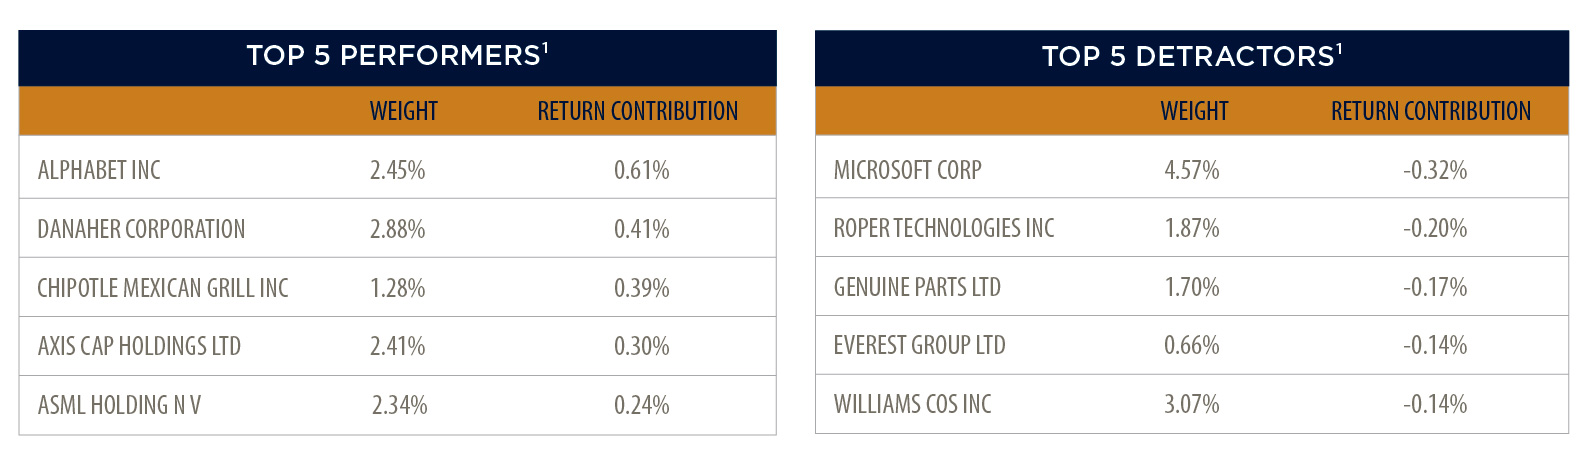
1) Past performance is not indicative of future results, and there is a risk of loss of all or part of your investment. The above does not represent all holdings in the Strategy. Holdings listed might not have been held for the full period. To obtain a copy of Johnson Asset Management’s calculation methodology and a list of all holdings with contribution analysis, please contact your service team. The data provided is supplemental. Please see important disclosures at the end of this document.
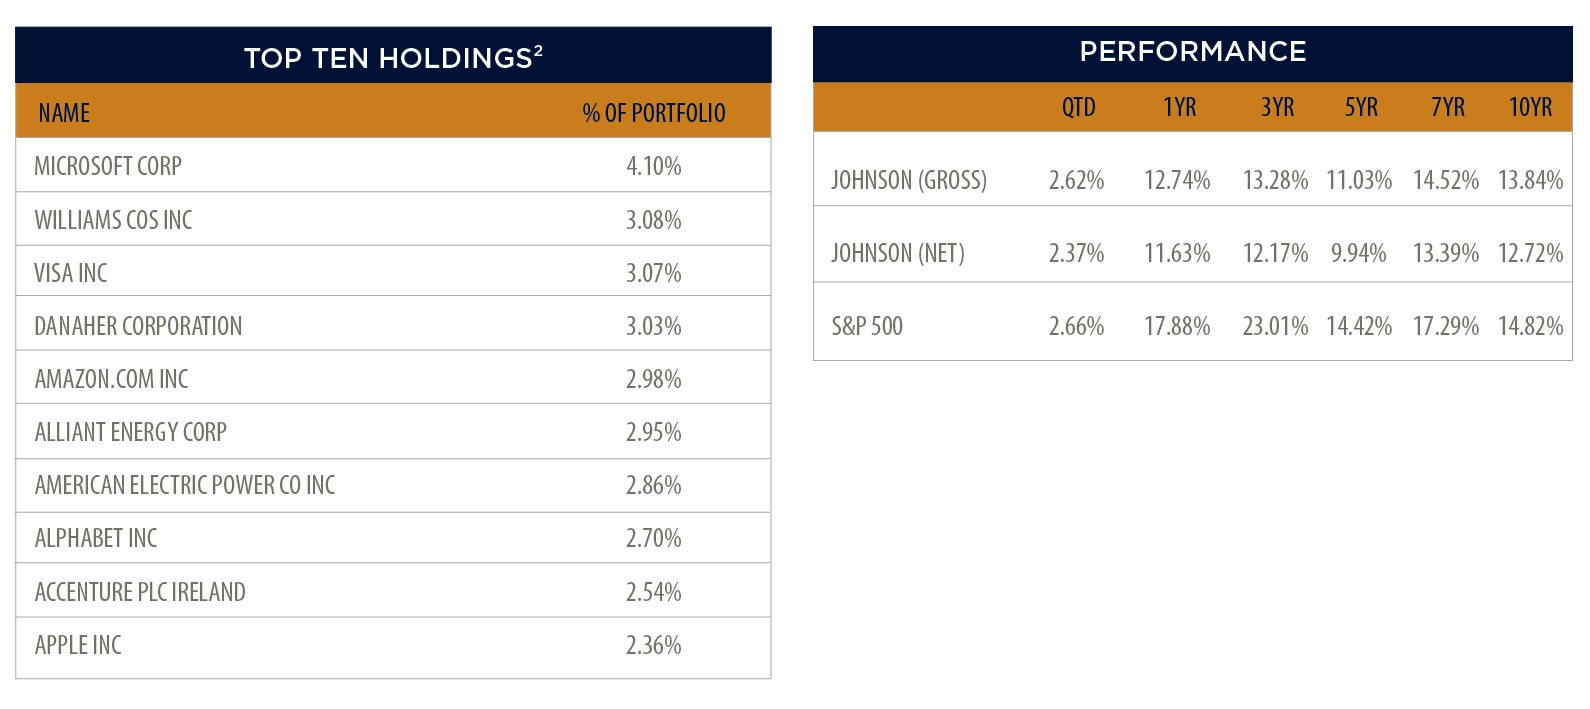
2) Holdings are subject to change. Past performance is not indicative of future results, and there is risk of loss of all or part of your investment. The data provided is supplemental. Please see disclosures at the end of this document.
Market Outlook and Portfolio Positioning
Despite trading roughly at the same place as it was heading into 2025, current market pricing reflects very low perceived risk with the forward S&P 500 P/E multiple at all-time highs. Simply put, investors are currently receiving limited compensation for taking on risk. Notwithstanding, the effects of last year’s rate cuts from the Fed should still be working their way through the economy and be potentially supportive of broader earnings revisions. Looking ahead, we will continue to monitor market developments closely and adjust accordingly to align with our long-term objectives. Those objectives are a focus on capital protection as well as enhancing the spending power of capital over time. We view the combination of a consistent valuation discipline and quality focus as the best means to reach those aims, regardless of the prevailing market environment.
The Johnson Equity Income Strategy seeks to outperform the S&P 500 over a full market cycle with a disciplined quality framework that provides investors with long-term capital growth, above average shareholder yield and reduced volatility through downside protection. For more information on our products and services, please contact a member of our Sales & Client Service Team at 513.389.2770 or info@johnsonasset.com.
Published 01/27/2026
Johnson Asset Management (JAM) is a division of Johnson Investment Counsel, Inc. (“JIC”), an independent and privately owned Midwestern based investment advisory firm registered with the Securities and Exchange Commission. Johnson Asset Management manages institutional separate account portfolios for a wide variety of for-profit and non-profit organizations, public agencies, public and private retirement plans, and personal trusts of all sizes. It may also serve as sub-adviser for mutual funds. JIC’s fees are available upon request and may be found in our Form ADV Part 2A. Performance data quoted herein represents past performance. Past performance does not guarantee or indicate future results. All data is current as of December 31, 2025 unless otherwise noted. Returns and net asset value will fluctuate. To determine if this strategy is appropriate for you, carefully consider the investment objectives, risk factors, and expenses before investing. Individual account management and construction will vary depending on each client's investment needs and objectives. Investments employing JIC’s strategies are NOT insured by the FDIC or by any other Federal Government Agency, are NOT Bank deposits, are NOT guaranteed by any Bank or any Bank affiliate, and MAY lose value, including possible loss of principal. Johnson Investment Counsel claims compliance with the Global Investment Performance Standards. The Equity Income composite includes all fee paying, fully discretionary, actively managed equity portfolios with a minimum value of $500,000 and an investment objective of Equity Income, benchmarked against the S&P 500 Index. The S&P 500 Index is a broad-based flagship benchmark that measures the performance of the largest companies listed on US stock exchanges. JIC’s policies for valuing portfolios, calculating performance and preparing compliant presentations, as well as a complete list of composite descriptions are available upon request. GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality of the content contained herein. Please contact our office at 513.389.2770 or 3777 West Fork Road, Cincinnati, OH 45247. All returns reflect the reinvestment of investment income (dividends and/or interest) and capital gains. Valuations and returns are stated in U.S. dollars. Trade date accounting is used. Portfolio returns are calculated using time weighed return methodology on a monthly basis. Net returns shown reflect gross performance less the highest fee schedule for this strategy. Actual client returns would also be reduced by brokerage commissions, custodial fees, and other client paid expenses detailed in JIC’s Form ADV Part 2A.