Summary
- Market Overview: Fixed Income delivered its strongest year since 2020, with the Bloomberg Aggregate Index returning +7.3% amid Fed rate cuts and easing inflation.
- Performance: The Johnson Core Fixed Income Strategy gained +8.01% net, outperforming the index by 72 basis points.
- Primary Drivers: Outperformance was led by yield curve positioning, with a focus on intermediate duration benefiting from curve steepening.
- Sector Allocation: An overweight to corporate bonds added value as spreads tightened during the year.
- Structured Exposure: Increased allocation to Agency MBS—along with strong security selection—enhanced returns and improved portfolio quality.
- Outlook: With signs of labor market cooling and potential for further rate cuts, the strategy remains focused on high-quality positioning, consistency, and stability across market environments.
Video Transcript
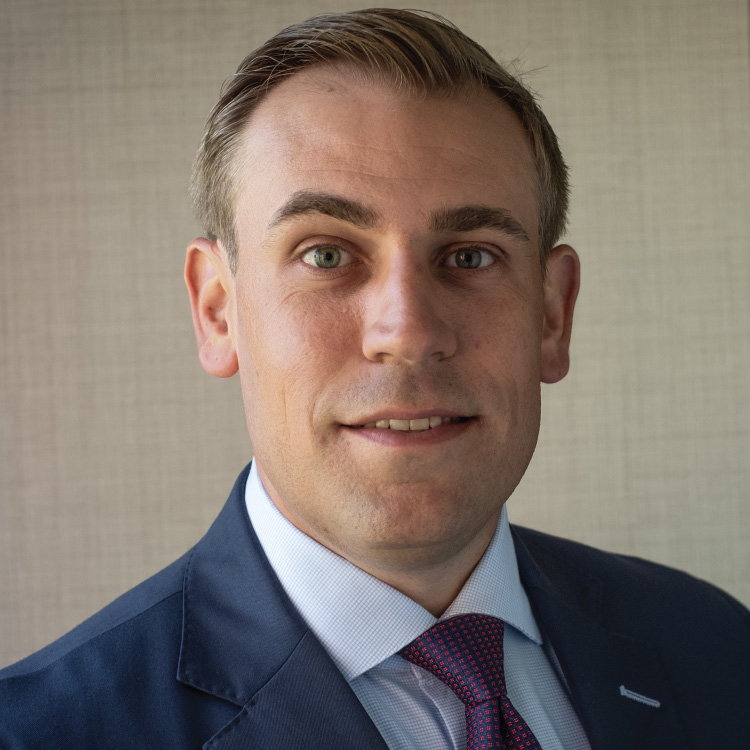
Hello. I’m Brandon Zureick, Senior Managing Director at Johnson Asset Management.
While headlines focused on the continued dominance of AI related stocks, Fixed Income quietly delivered its strongest year since 2020.
The Bloomberg Aggregate Bond Index gained 7.3%, supported by Fed rate cuts and easing inflation.
The Johnson Core Fixed Income strategy finished the year up 8.01% net of fees, outperforming the Index by 72 basis points.
Most of the strategy’s outperformance last year came from its yield curve positioning.
Early in the year, we shifted the Strategy’s key rate duration to a more bulleted focus in the intermediate part of the yield curve, which paid off as the yield curve steepened.
Our overweight to corporate bonds was also beneficial, as spreads tightened modestly throughout the year.
Agency Mortgage Backed Securities beat duration matched Treasuries by 171 basis points in 2025, marking their highest excess return since 2010.
The Strategy has been gradually increasing weight in Agency MBS as a way to maintain yield, but move higher in quality as corporate spreads have approached cycle lows.
Security selection within mortgages was also a positive contributor to performance, as lower coupon more stable duration bonds outperformed.
As we look ahead to next year, we believe our high-quality investment approach is well positioned for the current environment.
Most indicators of labor market activity suggest continued cooling.
This backdrop should support further interest rate cuts aimed at adjusting policy closer to the Fed’s estimate of neutral, around 3%.
As always, we remain committed to delivering high-quality fixed income portfolios designed to provide consistency and stability across a wide range of market environments.
Should you have any questions, please reach out to any member of the Johnson Team.
Published 01/28/2026
Johnson Asset Management (JAM) is a division of Johnson Investment Counsel, Inc. (“JIC”), an independent and privately owned Midwestern based investment advisory firm registered with the Securities and Exchange Commission. Johnson Asset Management manages institutional separate account portfolios for a wide variety of for-profit and nonprofit organizations, public agencies, public and private retirement plans, and personal trusts of all sizes. It may also serve as sub-adviser for mutual funds. JIC’s fees are available upon request and may be found in our Form ADV Part 2A. Performance data quoted herein represents past performance. Past performance does not guarantee or indicate future results. All data is current as of September 30, 2025 unless otherwise noted. Returns and net asset value will fluctuate. To determine if this strategy is appropriate for you, carefully consider the investment objectives, risk factors, and expenses before investing. Individual account management and construction will vary depending on each client's investment needs and objectives. Investments employing JIC’s strategies are NOT insured by the FDIC or by any other Federal Government Agency, are NOT Bank deposits, are NOT guaranteed by any Bank or any Bank affiliate, and MAY lose value, including possible loss of principal. Johnson Asset Management claims compliance with the Global Investment Performance Standards. The Institutional Core composite includes all fee paying, fully discretionary, actively managed institutional fixed income portfolios with a minimum value of $500,000 and an investment objective of broad investment grade, taxable fixed income, benchmarked against the Bloomberg U.S. Aggregate Index. The US Aggregate Bond Index is a broad-based flagship benchmark that measures the investment grade, US dollar denominated, fixed-rate taxable bond market. JAM’s policies for valuing portfolios, calculating performance and preparing compliant presentations, as well as a complete list of composite descriptions are available upon request. Please contact our office at 513.389.2770 or 3777 West Fork Road, Cincinnati, OH 45247. All returns reflect the reinvestment of investment income (dividends and/or interest) and capital gains. Valuations and returns are stated in U.S. dollars. Trade date accounting is used. Portfolio returns are calculated using time weighed return methodology on a monthly basis. Net returns shown reflect gross performance less the highest fee schedule for this strategy. Actual client returns would also be reduced by brokerage commissions, custodial fees, and other client paid expenses detailed in JIC’s Form ADV Part 2A.