Summary
- Market Backdrop: Q4 reversed earlier bond-market trends as labor-market concerns faded and election dynamics shifted expectations.
- Rates & Policy: Despite Fed rate cuts driven by labor-market weakness, long-term yields rose sharply amid expectations for pro-growth, potentially inflationary policies.
- Market Impact: Since September’s first rate cut, Fed Funds fell 100 bps, while the 10-year Treasury rose 87 bps, an unusual divergence.
- Performance Effect: Rising long-term rates created a modest headwind given the strategy’s slightly longer duration.
- Positioning: Portfolios remain defensively positioned as corporate spreads sit near multi-decade lows and spread-tightening potential appears limited.
- Outlook: Higher overall portfolio yields now offer an attractive entry point for high-quality fixed income, with a continued focus on resilience amid volatility.
Video Transcript
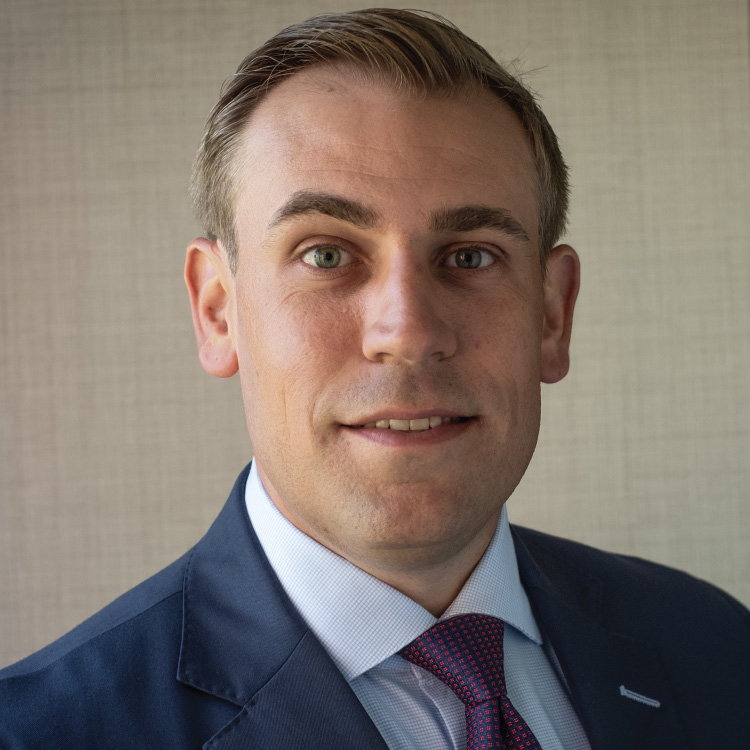
Hello, I’m Brandon Zureick, Managing Director with Johnson Asset Management.
The fourth quarter was largely a reversal of the themes that drove bond yields lower through the first nine months of the year.
While it feels like a distant memory, the market had grown increasingly nervous about the future health of the labor market.
The unemployment rate had risen nearly a full percent from it’s cycle lows, and you couldn’t read market commentary without hearing about the so called “Sahm rule” being triggered.
While far from a recessionary panic, the labor market weakness caught the Fed’s attention and prompted a series of rate cuts.
While the Fed’s gaze shifted towards the labor market, the bond market had other concerns.
As election odds tilted in favor of a Trump Whitehouse, the prospect of a pro-growth and somewhat inflationary policy slate pushed long-term yields higher.
In fact, from the day of the first rate cut in September, Fed Funds is now 100 basis points lower, while the 10Y closed the year 87 basis points higher.
Unusual to say the least!
This dramatic re-pricing in long term rates was a modest headwind to relative performance, given our somewhat longer duration stance versus benchmarks.
Looking forward, we continue to position portfolios in a more defensive manner.
With corporate bond spreads approaching their lowest levels in decades, we believe that the total return opportunity from spread tightening has greatly diminished.
While rising rates were a headwind to performance in the 4th quarter, overall portfolio yields are now approaching cycle highs once again and represent an attractive entry point for high quality fixed income.
As always, we remain committed to a high-quality approach that is built to withstand volatility and uncertainty.
Published 01/27/2025
Johnson Asset Management (JAM) is a division of Johnson Investment Counsel, Inc. (“JIC”), an independent and privately owned Midwestern based investment advisory firm registered with the Securities and Exchange Commission. Johnson Asset Management manages institutional separate account portfolios for a wide variety of for-profit and nonprofit organizations, public agencies, public and private retirement plans, and personal trusts of all sizes. It may also serve as sub-adviser for mutual funds. JIC’s fees are available upon request and may be found in our Form ADV Part 2A. Performance data quoted herein represents past performance. Past performance does not guarantee or indicate future results. All data is current as of September 30, 2024 unless otherwise noted. Returns and net asset value will fluctuate. To determine if this strategy is appropriate for you, carefully consider the investment objectives, risk factors, and expenses before investing. Individual account management and construction will vary depending on each client's investment needs and objectives. Investments employing JIC’s strategies are NOT insured by the FDIC or by any other Federal Government Agency, are NOT Bank deposits, are NOT guaranteed by any Bank or any Bank affiliate, and MAY lose value, including possible loss of principal. Johnson Asset Management claims compliance with the Global Investment Performance Standards. The Institutional Core composite includes all fee paying, fully discretionary, actively managed institutional fixed income portfolios with a minimum value of $500,000 and an investment objective of broad investment grade, taxable fixed income, benchmarked against the Bloomberg U.S. Aggregate Index. The US Aggregate Bond Index is a broad-based flagship benchmark that measures the investment grade, US dollar denominated, fixed-rate taxable bond market.
JAM’s policies for valuing portfolios, calculating performance and preparing compliant presentations, as well as a complete list of composite descriptions are available upon request. Please contact our office at 513.389.2770 or 3777 West Fork Road, Cincinnati, OH 45247. All returns reflect the reinvestment of investment income (dividends and/or interest) and capital gains. Valuations and returns are stated in U.S. dollars. Trade date accounting is used. Portfolio returns are calculated using time weighed return methodology on a monthly basis. Net returns shown reflect gross performance less the highest fee schedule for this strategy. Actual client returns would also be reduced by brokerage commissions, custodial fees, and other client paid expenses detailed in JIC’s Form ADV Part 2A.